October market update: Charts show October 2026 FastStats. Renton city history and mortgage-rate context are included. Four source-defined price ranges and six property-feature comparisons are included. This dated report is not a live listing feed.
Renton real estate / The seller’s complete guide / 98055
98055 housing market.A sharper plan for your sale.
Your competition is the next home a buyer would choose. Compare your ZIP, property type, inventory and financing conditions to build a stronger selling plan. Buying here—or selling and buying? Use the same evidence to plan your next move.
No signup to read the research. Start a conversation when you’re ready.
NWMLS FastStats · October 2026Residential + condosPrepared by Ask Anton
98055 homes for sale24Residential · month-end snapshot
Accepted offers9Residential · October 2026
Completed sales7Residential · October 2026
This snapshot describes the full ZIP postal market, which can extend beyond city boundaries. The 98178 report is boundary-area context, not a Renton-only subset.
01 / Start with the selling decision
A strong sale starts with the right comparison.
Renton city · October 2026 versus October 2025 · NWMLS InfoSparks. Percentage changes below are calculated from exported values.
MORE COMPETITION
+43.4% residential inventory.
Renton city had 337 residential listings at October month-end, versus 235 a year earlier. Closings fell from 99 to 80 (-19.2%). For a seller, a compelling launch price and presentation matter when buyers have more alternatives. For a buyer, those alternatives are worth comparing before making an offer.
PRICE AND SALES MIX
Both medians fell; the markets still differ.
The residential median was $752,499 (-4.7% year over year); the condo median was $357,000 (-4.5%). These medians reflect the mix of sales; they do not measure a gain or loss for the same home. Choose the right property type and bracket before interpreting the headline.
LONGER MARKETING TIME
Marketing time tells another story.
Residential median days to an accepted offer rose from 16 to 24, and the condo measure rose from 24 to 36. Both categories took longer among the homes that reached an accepted offer. These medians do not describe the eventual wait for every active listing. Use the property’s actual competition and the source’s longer history.
What the price bands reveal
Your price bracket matters more than the Renton headline.
Renton city · January–October 2026 versus January–October 2025. These city segments are not ZIP-specific results.
The Renton headline can hide the market for your home.
A luxury residential property and a condo may share a ZIP code while facing very different competition. Begin with the right category, then narrow to your price range, condition, location and features.
Use this report to identify the questions that matter. A pricing recommendation should also examine current listings, pending sales and recent comparable closings. The historical snapshot below cannot establish what a particular home will sell for today.
01
Price for the next buyer.
Explain why your home is compelling at its asking price compared with the available alternatives. Treat yesterday’s peak or your renovation cost as context, not a buyer’s obligation.
02
Prepare with a budget.
Prioritize the issues buyers will notice and the information they will need. Compare the cost and delay of improvements with an as-is sale before committing.
03
Set a review date.
Agree in advance on when to review showings, feedback, new competitors and offers. Respond to evidence rather than waiting indefinitely at a price the market has not accepted.
Let’s talk about your next move
Get your Renton market plan.
Pricing and preparation for sellers. Competition and payment questions for buyers. A coordinated plan if you’re doing both.
Your conversation
Ask in your own words.
Chat uses Functional cookies. Review to enable them.
Prefer a person? Email the team about your Renton sale or purchase. Email info@askanton.com.
You’re chatting with our digital assistant. Responses can make mistakes. Chat sessions are recorded. Verify important information before acting. About using Ask Anton By sending a message, you agree to our Terms of Use, including arbitration and use of your submissions in content, and acknowledge our Privacy Policy.
The deep dive / Six differences that matter
Your price bracket matters more than the Renton headline.
A stronger year-to-date count can coexist with slower recent sales. Condos, new homes and townhomes also need their own comparisons. Here is what the Renton evidence shows.
Renton city · NWMLS InfoSparks · retrieved November 12, 2026. YTD means January–October. Recent comparisons use August–October in each year. Arrows compare 2025 → 2026. Download the underlying segment data (CSV) ↓
01 / Residential price bands
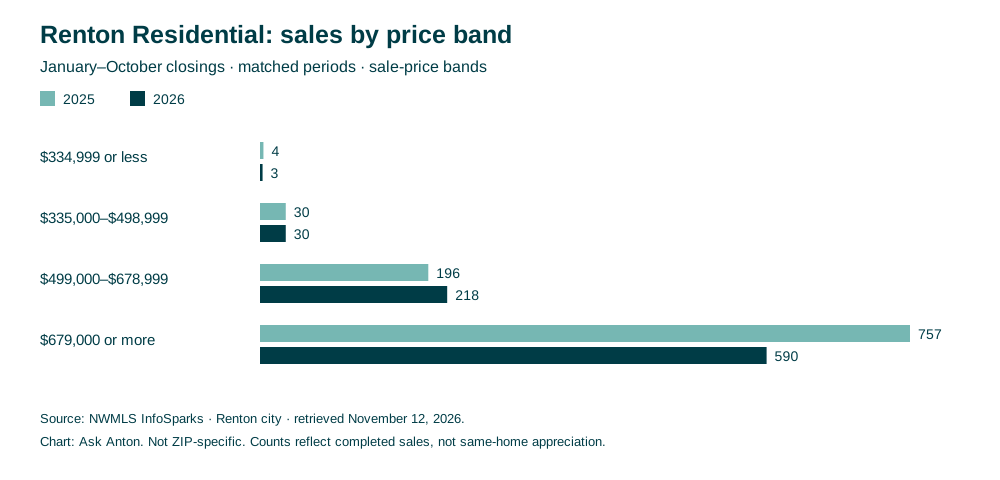
The $499,000–$678,999 band gained sales. The broad upper band slowed.
Residential YTD closings at $679,000 or more went from 757 → 590 (-22.1%). October inventory increased from 195 → 269, with source months of supply moving from 2.7 → 4.7.
Residential · Renton city. Closings: January–October. Inventory and source months of supply: October month-end. Every arrow compares 2025 → 2026.
Sale-price band*
YTD closings
Change
Inventory*
Months of supply*
$334,999 or less
4 → 3Small sample
-25.0%
1 → 4
0.8 → 4
$335,000–$498,999
30 → 30
0.0%
7 → 16
2 → 5.6
$499,000–$678,999
196 → 218
+11.2%
32 → 48
1.6 → 2.3
$679,000 or more
757 → 590
-22.1%
195 → 269
2.7 → 4.7
Residential: where sales are happeningJanuary–October closings · 2025 versus 2026
20252026
$334,999 or less
4
3
$335,000–$498,999
30
30
$499,000–$678,999
196
218
$679,000 or more
757
590
Bars begin at zero. Each property-type chart has its own scale. Exact counts and changes are in the table above.
The $499,000–$678,999 band recorded 196 → 218 YTD closings (+11.2%). This shift in completed-sale mix can affect the city median; it does not measure a change in the value of the same home.
Seller read: Start with the next home a buyer would choose. The $679,000-plus range is broad and includes very different properties; it is not a luxury-only category. Narrow by location, size, condition, ownership and features before choosing a launch price.
Only three residential closings occurred at $334,999 or less YTD in 2026. Small counts can produce dramatic percentage changes with little evidence of a lasting trend. These are the four ranges actually exported for Renton.
Identify the homes buyers will compare with yours.
A better year-to-date count does not mean the latest months strengthened.
In the $499,000–$678,999 residential band, matched August–October closings and accepted offers were lower even though YTD closings were higher:
69 → 66August–October closingsSame three months in each year
66 → 60August–October pending salesAccepted offers, not completed sales
32 → 48October inventoryMonth-end available listings
October median days to an accepted offer rose from 12 → 37 days. For the $679,000-plus band, recent closings went from 218 → 164, while recent pending sales went from 208 → 184.
Seller read: Use both the longer comparison and the most recent matched period. Set a review date before launch, then check showings, feedback, new competitors and accepted offers. A YTD gain alone is not a reason to hold an unsupported asking price.
Build a launch plan with a clear date to review the response.
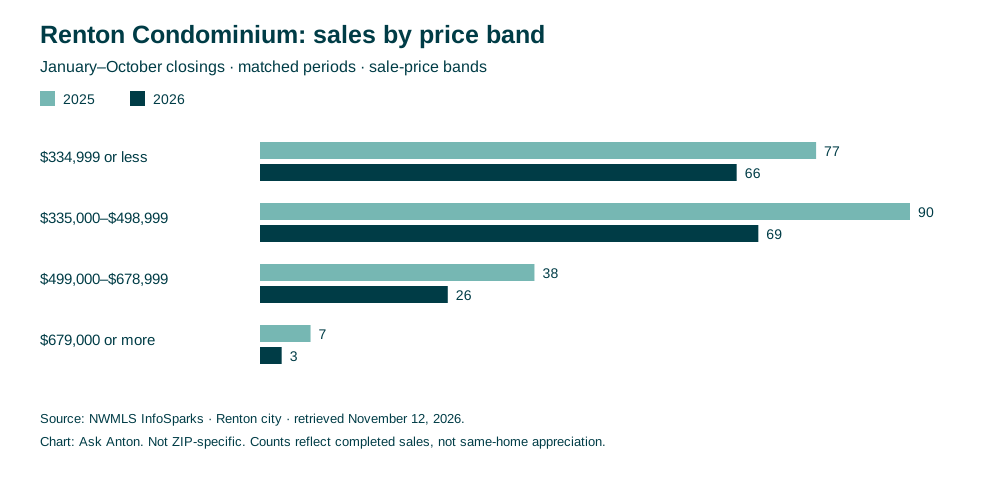
At $334,999 or less, YTD closings went from 77 → 66. October inventory changed from 38 → 37, while median days to an offer rose from 7 → 53.
The $335,000–$498,999 band has more competition.
YTD sales changed -23.3%. October inventory rose from 20 → 35, and source supply reached 5.3 months.
Missing prices are not zero-dollar sales.
The $679,000-plus band had three YTD closings and none in August–October 2026. Its October supply and median are unavailable. Thin activity cannot establish a reliable price trend.
Seller read: Compare within the building and relevant developments, including dues, assessments, condition, parking and financing eligibility. These statistics do not identify which association or financing issues caused sales to change.
Compare your condo with the units buyers can actually choose.
New-home sales fell faster than residential resales.
Renton city · January–October closings and October month-end inventory · 2025 → 2026
Property category
Construction Type
YTD closings
Change
Inventory
Residential
New Construction
61 → 25
-59.0%
33 → 44
Residential
Previously Owned
926 → 816
-11.9%
202 → 293
Condominium
New Construction
0 → 0
Not meaningful
2 → 0
Condominium
Previously Owned
212 → 164
-22.6%
79 → 82
New construction’s share of residential closings fell from 6.2% to 3.0%. Recent new-home closings also fell, from 17 → 6 in August–October. Residential resale inventory rose from 202 → 293.
No new-construction condo closings were reported in either YTD period. The residential construction counts describe the completed-sale mix; they do not prove that incentives, design, pricing or project-delivery timing caused the change.
Seller read: Compare a resale with nearby new homes on usable space, location, lot, condition, total cost and terms. Construction-type totals are separate from the price-band analysis, not a construction-by-price cross-tab.
See how your home competes with nearby new construction.
Waterfront is a small market with a different inventory pattern.
Renton city · January–October closings and October month-end inventory · 2025 → 2026
Property category
Waterfront
YTD closings
Change
Inventory
Residential
Only Waterfront
19 → 13
-31.6%
10 → 6
Residential
Exclude Waterfront
968 → 828
-14.5%
225 → 331
Condominium
Only Waterfront
9 → 4
-55.6%
2 → 2
Condominium
Exclude Waterfront
203 → 160
-21.2%
79 → 80
Waterfront residential YTD closings went from 19 → 13, while October inventory fell from 10 → 6. Waterfront condo YTD closings went from 9 → 4. This differs from the broader residential inventory increase.
Only 3 waterfront residential and 0 waterfront condo closings were reported in October 2026. Small samples limit monthly price comparisons. The waterfront flag does not establish shoreline access, dock condition, ownership rights or view quality.
Seller read: Compare verified waterfront features and rights. Do not transfer a condo result to a residential waterfront property or treat a view home as waterfront without checking its classification.
Build a waterfront comparison around the features and rights that matter.
Townhouse-style sales differ between residential and condo classifications.
Renton city · January–October closings and October month-end inventory · 2025 → 2026
Property category
Style Code
YTD closings
Change
Inventory
Residential
Townhouse
26 → 29
+11.5%
16 → 22
Condominium
Townhouse
55 → 52
-5.5%
19 → 16
Residential townhouse-style YTD closings rose from 26 → 29, while condo townhouse-style closings changed from 55 → 52. The recent August–October counts were lower in both categories: 11 → 8 residential and 19 → 13 condo.
Seller read: Confirm ownership and association obligations, then compare properties with similar usable space, age, parking, condition and location. A townhouse building style does not establish legal ownership. The source’s five exported style buckets do not cover every listing; their totals are not a replacement for the city total.
Match your townhome to comparable properties with the right ownership and features.
*InfoSparks uses sale price for sold-based metrics and original list price for non-closed metrics. A property can move between bands; inventory and closings are not a tracked group of the same properties. Source months of supply uses a trailing 12-month sales pace, not inventory divided by October closings. YTD and recent counts sum complete matched months. Monthly medians, supply and list-price ratios are not averaged to create YTD measures.
Actual Renton city exports, with residential and condominium results shown separately. Change the time window and graph style to see seasonality, direction and the difference between the two markets.
Closed Sales
ResidentialCondo
Compare like months and consider sample size. Seasonal patterns and property mix can affect the result.Exact chart values
Closed Sales · NWMLS InfoSparks · Renton city · through Oct 2026
Price measures reflect the properties that sold. A changing mix can move this line without the same home changing value by the same amount.Exact chart values
Median Sales Price · NWMLS InfoSparks · Renton city · through Oct 2026
Compare inventory with accepted offers and closings. More choices and fewer transactions call for a clear reason to choose your home: pricing, condition, terms or a combination.
For buyers: test the opportunity.
More inventory can expand your choices, but it does not make every listing negotiable. Use comparable sales, property condition, competing offers and your payment budget to build an offer.
City results are not sums of the ZIP reports. InfoSparks median days and median list-price ratios also differ from FastStats measures; compare each series only with its own definition. Rolling 12-month medians are exported from the source, not averages of monthly medians. Retrieved November 12, 2026.
Turn the trend into a plan for your property.
Get help comparing the homes that matter to your sale or purchase.
Compare the same periods in both years. Switch property type before drawing a conclusion about your home.
Showing residential · October 2026 vs 2025. Inventory and supply always show the October snapshot. 7 closed sales across the selected ZIP in October 2026.
Median sale price
October
20252026
Use the median to understand the sales mix. Price your home from comparable properties, condition and competing inventory.Exact values and source changes
Residential · October · Median sale price
ZIP
2025
2026
Source change
98055
$810,000
$596,500
-26.4%
Closed sales
October
20252026
Completed sales show the size of the sample. A handful of luxury or entry-price closings can move the median sharply.Exact values and source changes
Residential · October · Closed sales
ZIP
2025
2026
Source change
98055
14
7
-50.0%
Pending sales
October
20252026
Accepted offers help track buyer activity. A pending sale can still fail to close; this count is not a closing forecast.Exact values and source changes
Residential · October · Pending sales
ZIP
2025
2026
Source change
98055
9
9
0.0%
New listings
October
20252026
New listings add competing choices. Review the properties entering your price bracket before you choose a launch price.Exact values and source changes
Residential · October · New listings
ZIP
2025
2026
Source change
98055
10
13
+30.0%
Homes for sale
October
20252026
Available inventory is a snapshot, not a flow to add across months. More alternatives make condition and positioning more consequential.Exact values and source changes
Residential · October · Homes for sale
ZIP
2025
2026
Source change
98055
20
24
+20.0%
Months of inventory
October
20252026
Use the source supply measure as context for negotiating conditions. It is not a prediction of how long your home will take to sell.Exact values and source changes
Residential · October · Months of inventory
ZIP
2025
2026
Source change
98055
1.9 mo
2.6 mo
+36.8%
Days on market until sale
October
20252026
This source measure describes homes that sold. It excludes the full eventual marketing time of homes still waiting for a buyer.Exact values and source changes
Residential · October · Days on market until sale
ZIP
2025
2026
Source change
98055
39 days
40 days
+2.6%
List price received
October
20252026
This ratio does not account for concessions. It is not a seller net-proceeds estimate and should not be treated as a sale-to-original-price measure.Exact values and source changes
Residential · October · List price received
ZIP
2025
2026
Source change
98055
98.6%
98.8%
+0.2%
Average sale price
October
20252026
Compare the average with the median. A few expensive transactions can pull the average away from the typical transaction in the sample.Exact values and source changes
Residential · October · Average sale price
ZIP
2025
2026
Source change
98055
$863,343
$620,214
-28.2%
What does this mean for your asking price?
Compare your property with the homes buyers can choose today.
The 30-year benchmark eased from 7.24% the prior week to 7.18%, but remained above the year-earlier 6.22%. A recent decline can help payment math without returning affordability to last year’s level.
2026 mortgage rates: 30-year and 15-year fixed
30-year fixed15-year fixed
National conventional conforming purchase-loan averages. These are interest rates, not APRs or personalized quotes. Jumbo, condo and individual borrower pricing can differ. The vertical scale begins at 4% to make weekly movement readable.Exact chart values
2026 mortgage rates: 30-year and 15-year fixed · Freddie Mac PMMS · weekly · through Nov 5, 2026
These are adjustable illustrations, not loan offers or qualification results. Start with your lender’s quote if you have one.
Other monthly housing costs start at an illustrative $1,200. Replace this with your property taxes, insurance, HOA dues, mortgage insurance and other recurring costs. This is not a Renton tax or insurance estimate. Maintenance, closing costs and cash reserves need separate budgets. All scenarios use a 30-year term and the same down-payment percentage.
Illustrative loan amount$640,000$160,000 down
Principal & interest / month$4,33630 years at 7.18%
With your other monthly costs$5,536Estimate, before unbudgeted expenses
Same home, different rate: monthly payment
Monthly principal & interest
At the same loan amount, a rate one percentage point higher changes monthly principal and interest by $441. This is a sensitivity calculation, not a rate forecast.Exact chart values
Same home, different rate: monthly payment · Illustration · $640,000 loan · 30 years
Period
Monthly principal & interest
6.18%
$3,911
6.68%
$4,121
7.18%
$4,336
7.68%
$4,554
8.18%
$4,777
Same payment budget, different purchase price
Illustrative purchase price
This holds principal and interest constant. The cash down payment changes with the price. Taxes, insurance, HOA, qualification and loan limits are excluded; this is not an approved buying budget.Exact chart values
Same payment budget, different purchase price · Illustration · $4,000/mo P&I · 20% down
Period
Illustrative purchase price
6.18%
$818,101
6.68%
$776,456
7.18%
$738,078
7.68%
$702,661
8.18%
$669,926
SELLING
Understand the buyer’s constraint.
Compare a price adjustment with a possible seller credit using lender-confirmed costs and limits. Evaluate your net proceeds and the buyer’s actual benefit; a credit and a price cut are not interchangeable.
BUYING
Make today’s payment work.
Compare price, cash needed and total monthly costs. A future refinance is uncertain. Choose a payment you can carry under the loan terms you actually accept.
SELLING + BUYING
Model both sides of the move.
A low existing mortgage rate is only one input. Compare equity released, replacement-home costs, moving costs, temporary overlap and your timeline.
What does the payment mean for your plan?
Bring your price range and timing. We’ll help frame the property questions and the financing questions to take to a lender.
Residential inventory was 24 homes (+20.0% year over year), with 2.6 mo of reported supply. The source's days-on-market measure was 40 days.
Seller read: More homes were competing for attention than a year earlier. Make your price and presentation credible against the alternatives in your segment. Only 7 residential closings support this monthly median. Use the longer comparison and individual comparables before setting an asking price.
Buyer read: Compare your choices in this ZIP with the specific home’s condition, asking price and competing offers. More inventory can create options, but a ZIP average cannot establish the discount or concessions available on an individual listing.
Condo comparison: $460,675 median, 4 sales, 4.8 mo of supply. Different property types need separate pricing reviews.
ZIP coverage: 98055, 98056, 98057, 98058 and 98059 are the main Renton postal markets. 98178 is included as boundary-area context from the City ZIP layer. Postal markets can include property outside Renton; the full ZIP report is not a Renton-only subset. Use the physical property location to verify city jurisdiction. City of Renton ZIP geography · Postal-code reference.
Your competitive set / Price and property features
Find the market your home actually competes in.
Compare the four NWMLS Renton price bands, or switch to construction type, bedrooms, square footage, lot size, waterfront or building style. These are Renton city segments, not ZIP-specific cross-tabs. Each feature is analyzed separately.
Read the price basis: InfoSparks uses sale price for metrics based on sold data and original list price for non-closed metrics. A home can move between brackets. Do not divide this month’s bracket inventory by closings and call it the source’s months of supply. Source supply uses a trailing 12-month average sales pace.
Closed Sales by price range
October 2025October 2026
Each bar begins at zero. On a small screen, scroll horizontally to read the full chart. Missing values are labeled, not replaced with zero. Full range boundaries and exact values appear below.
Residential · Renton city · Closed Sales. Changes calculated from exported values.
Price Range
Oct 2025
Oct 2026
Change
Oct 2026 closings
$334,999 or Less
0
0
Not meaningful
0 · small sample
$335,000 to $498,999
6
9
+50.0%
9
$499,000 to $678,999
20
20
0.0%
20
$679,000 or More
73
51
-30.1%
51
A zero sales count is a reported result; an unavailable price is not a $0 sale. Fewer than five closings is flagged as a small sample here. No median is reconstructed from other medians, and no percentage change is computed from a zero baseline.
October inventory269
October closings51
October median sale price$880,000
$679,000 or More: Closed Sales
Residential
Two years of monthly observations. Blank periods break the line. Use the sales count alongside price and ratio changes; price-bracket medians are constrained by the selected range.Exact chart values
$679,000 or More: Closed Sales · NWMLS InfoSparks · Renton city · Residential · Oct 2026
Period
Residential
2024-11
69
2024-12
56
2025-01
54
2025-02
44
2025-03
84
2025-04
65
2025-05
96
2025-06
97
2025-07
99
2025-08
77
2025-09
68
2025-10
73
2025-11
48
2025-12
52
2026-01
36
2026-02
44
2026-03
83
2026-04
63
2026-05
68
2026-06
72
2026-07
60
2026-08
55
2026-09
58
2026-10
51
Seller read: make the comparison specific.
Start with the properties buyers can choose in this segment. Compare their asking prices, condition and terms with recent comparable closings, then decide where your home should compete. New construction and resale can attract different buyers and offer different incentives.
Buyer read: narrow the search, then verify.
Use the segment to find relevant alternatives. A more expensive home, larger lot or newer build is not automatically better value. Review condition, usable space, ownership rights and the full cost before deciding what to offer.
InfoSparks metric definitions · Retrieved November 12, 2026. Price measures exclude concessions. Source data can be revised. Property classifications and price ranges alone do not establish comparability.
From research to a sale / Your seller playbook
Build the plan around your property, your net, and your next move.
Use the market report to ask better questions. Then build a property-specific plan with actual competitors, preparation estimates and a closing-cost worksheet.
BEFORE YOU SPEND
Define the outcome.
Write down your target move date, mortgage payoff, available preparation budget and how much flexibility you have. If you are buying again, review financing and the cost of overlapping two homes before choosing a listing date.
BEFORE YOU PRICE
Build three comparable sets.
Recent closings show completed outcomes. Pending properties indicate where buyers have acted, although their final terms may not be known. Active listings show what your next buyer can choose instead. Match ownership type, location, size, condition and features.
BEFORE YOU LAUNCH
Choose a preparation budget.
Separate necessary repairs, presentation work and optional upgrades. Request written estimates and compare the likely delay and carrying costs with selling in current condition. Avoid assuming that every improvement returns its cost.
The Renton comparison checklist.
Location and physical features
A postal median cannot price a lake view, waterfront access, a busy-street location, a steep lot or a different neighborhood. Review access, parking, usable outdoor space, condition and the buyer’s alternatives. Verify boundaries and property facts rather than treating a neighborhood name as proof of value.
For a condo or condominiumized home, assemble association documents, dues, reserve information, insurance and known assessments. For improvements or additional living space, gather permit records and verify the use. A townhome’s appearance alone does not establish its legal ownership or MLS category.
A planning sequence—not a promised sale or closing timeline.
Stage
Decision
Evidence to review
Prepare
What to repair, disclose and present
Property records, condition, written estimates, association documents when applicable
Price and launch
Where the home competes and how buyers will see it
Comparable properties, photography, marketing plan, access and showing arrangements
Review response
Whether price, presentation or terms need adjustment
Showings, repeated feedback, new competition and offers; set a review date with your broker
Evaluate offers
Which combination of net, certainty and timing fits
Financing, contingencies, credits, deposits, closing schedule and possession terms
Close and move
How to satisfy agreed obligations and coordinate the move
Contract deadlines, repair agreements, payoff information, settlement statement and possession plan
Ask for a net sheet at more than one price.
Start with sale price, then subtract loan payoffs, negotiated brokerage compensation, applicable taxes, title and escrow charges, seller credits, repairs, prorations and other transaction costs. Add preparation and carrying costs when comparing strategies. An estimated net sheet is not the final settlement statement.
Low activity can reflect price, exposure, access, presentation or a limited buyer pool. Review those factors together. Repeatedly making small reductions without addressing the cause can consume time while new competitors enter the market.
This checklist is educational. Your broker, escrow team, lender and other advisers should confirm property-specific requirements, costs and deadlines. No chart predicts an individual sale price or guarantees a marketing period.
05 / Protect your net
The best price is only part of the decision.
Compare the complete offer.
Look at credits, preparation costs, financing, contingencies and timing alongside price. An aggregate list-price ratio cannot tell you the proceeds from your own sale.
Get specific estimates and a realistic schedule. If the project delays your move, include carrying costs and the risk that buyers will value the work differently.
Buyers / Use the same evidence from the other side
Yes, buyers can use this report too.
The seller focus helps explain how homes compete. For a buyer, those same measures help narrow the search, assess negotiating room and avoid making an offer from a citywide headline.
01 / CHOICES
Find the market you can buy in.
Filter residential and condos separately. Compare your ZIP and price range, then look at the actual available homes. More listings do not necessarily mean more properties that fit your needs.
02 / TERMS
Make a supported offer.
Use recent comparable sales, the property’s listing history, condition and competing offers. Explore price, repair or closing-cost terms where appropriate. Keep inspection, financing and other protections tied to the specific transaction.
03 / COST
Look beyond the sale price.
Use the rate scenarios, then obtain lender quotes and property-specific expenses. For condos, review dues, reserves, assessments, insurance and financing eligibility. For houses, budget for condition and maintenance.
What the data can tell you
How much choice exists, how transactions are changing, how long sold homes were marketed and how outcomes differ by property type.
What still needs a property review
What this home is worth, whether the seller will negotiate, what repairs are needed and whether the financing and monthly costs work for you.
Build a buying plan from the data.
Choose Buying or Selling and buying in the form above.
CSV period: October 2026. Original FastStats PDFs are available below. City and segment graphs include their source CSVs; charts download individually as SVG files.
Yes. Compare property types and ZIPs, inspect the city trends, and use the payment scenarios to frame a search and offer strategy. Then review the actual property, comparable sales, condition, financing and competing offers. More inventory does not guarantee a discount on every home.
Are the mortgage rates a quote for my Renton purchase?
No. The chart shows dated Freddie Mac national averages for conventional conforming purchase loans. Your rate and APR depend on the loan, credit, down payment, fees, lock period and property. Jumbo and condo financing can differ. Ask a lender for a property-specific quote and compare the full monthly cost.
Should I wait for rates to fall before buying or selling?
The report does not forecast rates. Compare a move you can afford under today’s quoted terms with the costs and uncertainty of waiting. If you are selling and buying, model net proceeds and replacement-home costs together. Do not rely on a future refinance to make the initial payment affordable.
What is my Renton home worth?
A ZIP median is a starting point for market research, not a property valuation. A useful pricing review compares your location, property type, size, condition and features with recent closings, pending properties and current competitors. Ask for a supported range and a selling plan.
Should I sell now or wait?
Start with your move, carrying costs and financial flexibility. Compare the likely net proceeds and timing risks of selling now with the cost of waiting. A seasonal pattern or changing median cannot guarantee a better future price.
Why separate houses and condos?
Residential and condominium properties can have different inventory, pricing and buyer pools. These reports preserve the MLS categories. Residential should not be assumed to mean detached houses only; confirm the property classification when selecting comparable listings.
Does a lower median mean my home lost that much value?
No. The median depends on which homes sold. Changes in size, condition, location and the share of luxury sales can change it. These aggregate reports do not follow the same properties over time.
Are Renton city and Renton ZIP codes the same market?
No. Postal areas are not municipal boundaries. The six ZIP reports are separate postal markets; their medians are not combined into a Renton city median. Use the physical property location for a city-specific comparison.
Why include 98178 alongside the five Renton ZIPs?
98055, 98056, 98057, 98058 and 98059 are the five main Renton postal markets. The City ZIP layer also highlights 98178. Its full postal-market report is boundary-area context and includes property outside Renton. Postal boundaries do not establish city jurisdiction; verify the physical property location.
Should I remodel before listing?
Scope repairs and presentation work against actual competing properties. Compare the cost, delay and uncertainty of the project with selling in current condition. Spending more does not guarantee a higher sale price or a higher net.
Do I need to sign up to read the data?
No. Charts and aggregate CSV downloads are available without a signup. If you choose to use the digital assistant, review its disclosures and edit your message before sending.
Ready to make this specific to you?
Bring your property, budget and timing into the conversation.
Matched periods. Monthly and year-to-date comparisons use the periods printed in each report. The nine source measures are extracted separately for residential and condo properties. Source percentage changes are retained, including rounding.
Inventory. Inventory and months of supply are monthly snapshots; the source has no year-to-date value for them. Selecting year to date leaves those two charts explicitly on the monthly period. Months of supply is reproduced from FastStats, not recalculated as inventory divided by this month’s closings.
Geography. ZIPs are postal-market geographies and may include areas outside Renton city. Counts can be summed across the six source ZIPs as a postal-market total. Medians, ratios, days on market and supply are not summed or averaged into a citywide statistic.
Price and market time. Medians describe the mix of completed sales, not appreciation of the same home. The report’s days-on-market measure is preserved under its own label; it is not relabeled as a median or cumulative days active. Price and list-price measures exclude concessions and down-payment assistance.
Small samples. Sales counts appear alongside prices. A large percentage change based on a few closings is not proof of a lasting trend. Individual comparable properties and longer matched periods are necessary before making a pricing recommendation.
City history. Renton city was selected in NWMLS InfoSparks. Sixteen original CSV exports cover January 2023–October 2026 and separate Residential and Condominium. Original exports are archived with hashes and available beneath their charts. InfoSparks days on market runs from listing to an accepted offer. Closed-based months of supply divides month-end inventory by average monthly closings over the prior 12 months; pending-based supply uses the corresponding pending pace. Price filters use sale price for sold-based metrics and original list price for non-closed metrics. Median list-price ratios retain their export labels and exclude concessions. These measures are not substituted for FastStats averages. See the source definitions.
Rates and scenarios.Freddie Mac PMMS weekly national averages are shown through November 5, 2026, checked November 12. Payment scenarios use fixed-rate monthly amortization over 360 payments. They are calculated illustrations, not observed Renton loan pricing or forecasts. No causal effect of rates on Renton prices is estimated.
Coverage and limitations. October ZIP FastStats and 46 months of Renton city InfoSparks history are included. Four source-defined price ranges, construction type, bedrooms, square footage, lot size, waterfront and style code are included for Renton city. These are separate dimensions, not all possible cross-filter combinations or ZIP-specific price brackets. Source segment totals are not forced to equal all-category totals; differences are disclosed beside the relevant views. No property valuation is inferred from a city or ZIP median.
Educational market information. This is a dated snapshot and may be revised by the source. It is not an appraisal, a guaranteed price, a promise of timing or a substitute for property-specific advice. See brokerage disclosures, Privacy and Terms.